

Grant Cash Advance
by Kikoff Inc.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
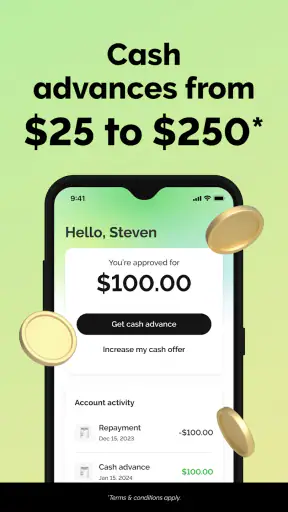
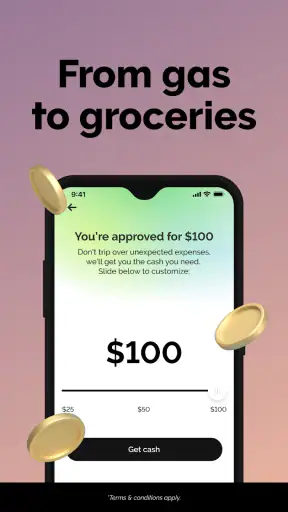
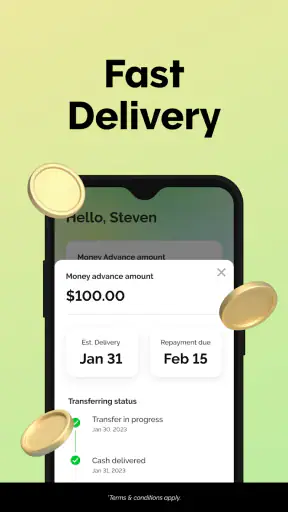
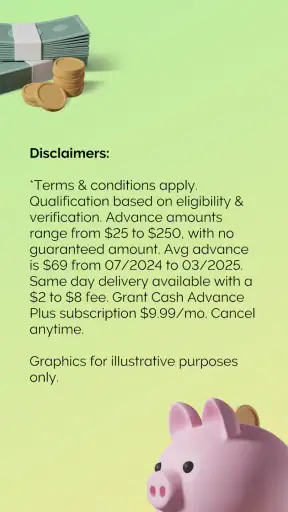
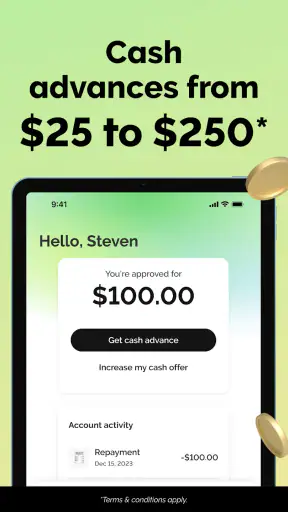
 Analysis by Getfullapps
Grant Cash Advance is a finance app from Kikoff Inc. that caught my attention because it focuses on getting cash to people who may not want to go through a traditional credit application. I approached it less like a quick-money advertisement and more like a financial tool that deserves careful checking before use. The central question is not simply whether an advance is convenient, but whether the app gives me enough control and clarity when money is tight.
In my experience, the app is most interesting for a short, specific cash gap: a bill arriving before payday, a necessary purchase, or an unexpected expense that cannot reasonably wait. It is not something I would treat as extra income, and I would not use it to cover a recurring monthly shortfall. That distinction matters because an easy application can make borrowing feel less serious than it really is.
The app is free to download and has an Everyone content rating, which makes it approachable for a broad audience. Its store presence is also substantial, with over one million installs, around a 4.8 average rating, and roughly 118 thousand ratings. Those figures suggest that many people find the experience useful, but they do not replace reading the terms shown during the application. A high rating can tell me that the product is popular; it cannot decide whether a cash advance fits my own budget.
How I judge the app before trusting it with financial information
Grant Cash Advance belongs to the finance category, where trust should come from visible choices rather than polished screens or reassuring language. I pay attention to what the app asks me to provide, why each piece of information appears necessary, and whether I can review important details before committing. The developer shown for the app is Kikoff Inc., so that identity is useful to check whenever I am making sure I have selected the intended application rather than an imitation.
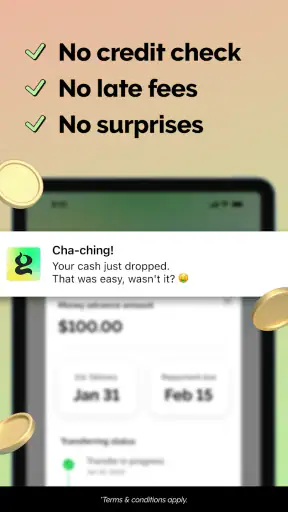
The store summary presents the service as a way to get cash without a credit check or interest. I would still treat those words as the beginning of my review, not the conclusion. “No interest” does not automatically mean “no cost,” and a cash advance can still affect my future cash flow through repayment timing or other terms. Before accepting anything, I would look closely at the amount I receive, the amount expected back, the repayment date, and every fee or condition displayed in the final confirmation.
That final review is especially important because financial apps often turn several separate decisions into one smooth flow. I prefer to slow down at each screen instead of tapping through automatically. If the app presents a summary before submission, I would save or record the key details for my own budget. If a term is unclear, I would not rely on the store description to interpret it; I would use the explanation shown in the app or contact the relevant support channel.
One practical strength of a dedicated cash-advance app is focus. Unlike a general banking app, it is built around a single urgent need, so I can quickly determine whether the product is even relevant. The trade-off is that the narrow purpose can encourage rushed decisions. When I am stressed about money, a short path to an application is convenient, but it also makes a pause-and-check routine essential.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Controls I would check during setup
I would begin by confirming the app identity, developer name, and version before entering sensitive information. The current version is 2.64.1218, and the minimum operating-system requirement is Android 7.0. Those details are useful for compatibility, but they are also a reminder to keep the app updated through the official store rather than installing an altered copy from an unknown source.
During setup, I would read every permission request instead of approving everything as a bundle. A permission should have a clear connection to the task I am trying to complete. If a request feels unrelated, I would pause and investigate it through the app’s explanations and the operating system’s permission settings. I would also check whether permissions can be denied or later withdrawn without losing access to unrelated parts of the phone.
Account control matters just as much as the initial application. I would look for a clear route to review profile information, update contact details, manage connected financial information, and contact support. I would also want to know how to stop using the service after an advance has been repaid. A trustworthy experience should not make it difficult to understand what remains active or how to request help.
My preferred workflow is simple: install the app, inspect the permission requests, read the account and advance terms, and only then decide whether to continue. I would not enter banking credentials while connected to an unfamiliar public network, and I would avoid reusing a password from email or social media. These are ordinary precautions, but they are particularly important when an app deals with identity and money.
I would also keep notifications under control. A finance app may need to remind me about an upcoming repayment, but I would not want sensitive account details displayed openly on a lock screen. Checking notification previews in the phone’s settings is a small step that gives me more privacy without interfering with useful reminders.
The moments when privacy deserves extra attention
The most sensitive part of using Grant Cash Advance is not browsing the app; it is the point where I provide financial and personal information to determine eligibility or arrange an advance. I would read the privacy and consent language on those screens rather than assuming that a short application means limited data collection. The important question for me is what information is requested, how it is used, and which choices are optional.
I would be especially careful with any request involving financial accounts, identity documents, contact information, or transaction details. Before continuing, I would check whether the app explains the purpose of the request in plain language. I would also look for a distinction between information required to provide the service and information used for optional communications or personalization. Those distinctions help me make an informed choice instead of accepting every possible use automatically.
Another useful habit is to review the app’s privacy controls after the account is created, not just during registration. If there are settings for communications, connected accounts, or data sharing, I would adjust them immediately to match what I actually need. I would take screenshots or notes of important consent choices so I can recognize later if something changes.
I do not assume that a finance app is unsafe simply because it requests sensitive information. A cash-advance service may reasonably need information to verify identity and assess an application. My concern is whether the request is explained and whether I can see the consequences before agreeing. Clear consent is more valuable than a reassuring slogan.
I would also avoid discussing account details through unofficial social-media messages. If I needed assistance, I would use the support route presented inside the app or its official store presence. I would never send a password, one-time security code, or complete banking credentials to someone who contacts me unexpectedly.
A realistic use case and the repayment decision
Imagine that my car needs an essential repair two days before payday. I could open the app, review whether I am eligible, and compare the advance terms with the cost of delaying the repair or using another source of funds. Before accepting, I would write down the expected repayment date and subtract that amount from my next paycheck in my budget. If doing so left me unable to pay rent, utilities, food, or another committed bill, I would not take the advance.
This is where the app’s “fast cash” appeal needs a practical boundary. Speed helps when an expense is genuinely urgent, but speed does not improve affordability. I would use the app only when I already know where repayment will come from. I would not take a second advance to cover the first one, and I would not use it for discretionary shopping, entertainment, or a purchase that can wait.
The no-interest positioning may make the service look simpler than a credit card or a conventional loan. In some situations, that can be an advantage, particularly if the alternative carries interest. But I would compare the complete cost and timing, not just the interest label. A bank overdraft, credit card, employer-based option, or help from a trusted person may be better depending on the exact terms and my ability to repay.
There is also a difference between avoiding a credit check and avoiding financial consequences. If the app does not use a conventional credit check, that may make access easier for someone with limited credit history. It does not remove the need to plan around repayment. I would regard the service as a temporary bridge, not a method for repairing a budget that is consistently short.
Who will benefit and who should choose another option
I can see the appeal for someone who needs a modest, short-term bridge and wants a focused mobile application instead of visiting a branch. It may also suit a person who has limited access to conventional credit and is willing to read the terms carefully. The free download lowers the barrier to exploring the service, although the actual financial terms still deserve close attention.
I would be more cautious if my income varies heavily, my next payday is uncertain, or several bills are already overdue. In those situations, a fixed repayment expectation can create more pressure. A nonprofit financial counselor, a negotiated payment plan, an emergency assistance program, or a traditional bank product may be more appropriate. The best alternative depends on the situation, but the key is to choose an option that addresses the underlying problem rather than extending it.
I would also skip the app if I am uncomfortable providing the information required for a financial application or if I cannot understand the consent screens. That is not a criticism of the product; it is a personal boundary. A finance app should be used only when I understand what I am authorizing and feel able to protect my account.
Compared with a credit card, an advance can feel more direct and may avoid interest in the way the service presents it, but a credit card may offer a longer repayment structure or more familiar account controls. Compared with a bank loan, an advance may be faster and less formal, while a bank may provide clearer long-term repayment planning. Compared with overdraft protection, the advance may be easier to separate from everyday spending, but overdraft terms vary widely and should not be assumed to be cheaper.
The right comparison is therefore not “which app is fastest?” It is “which option gives me a manageable repayment date, understandable costs, and enough control over my information?” Grant Cash Advance can be reasonable when it wins that comparison for a particular emergency. It is not automatically the best choice because it is convenient.
What I would do after receiving an advance
After accepting an advance, I would immediately add the repayment date to my calendar and set a personal reminder earlier than the official due date. I would keep the repayment amount in a separate part of my budget rather than treating the next paycheck as fully available. This simple separation reduces the chance that the money is accidentally spent twice.
I would review the account periodically and remove access that I no longer need, where the app and operating system allow it. I would also check notifications for unexpected changes, requests, or account activity. If something looked unfamiliar, I would contact support through an official channel before taking action.
Once the advance is settled, I would decide whether keeping the app installed still serves a purpose. Removing an unused finance app is a reasonable privacy habit, but I would first make sure I have saved any records I need and understand how to reach support if a later question arises. Deleting the icon alone is not the same as closing an account, so I would look for the proper account-management process.
The app’s popularity is encouraging, and its 7.8 thousand reviews show that users have taken time to discuss their experiences. Still, reviews are best used to identify recurring questions or friction points, not as a substitute for reading my own agreement. Individual financial circumstances differ too much for another person’s positive experience to guarantee that mine will be the same.
My cautious verdict
Grant Cash Advance is a focused finance app that may be useful when I need a temporary cash bridge and can repay it on schedule. I like the straightforward purpose, the free entry point, and the possibility of considering an advance without a conventional credit check. The strong user response and broad adoption make it worth investigating, but they do not remove the need for careful judgment.
My main reservation is built into the product category: fast access can encourage fast decisions. I would judge the app by the clarity of its terms, the explanation behind its information requests, and the controls available for managing my account and communications. I would not accept an advance until I had checked the full repayment obligation and confirmed that it fits comfortably into my next budget cycle.
For a one-off emergency with a known repayment source, I would consider trying it. For repeated shortfalls, uncertain income, or any situation where repayment would force me to neglect essential bills, I would choose a different route. The safest way to use Grant Cash Advance is as a carefully planned bridge, never as a replacement for stable income or a workable budget.
Overall, I would recommend exploring it with caution rather than recommending it automatically. Its value depends less on how quickly I can apply and more on whether I retain control at every step: what I share, what I accept, when I repay, and when I stop using the service. That is the standard I would apply before trusting Grant Cash Advance with a real financial need.
Pros
- Quick and easy loan approval process.
- User-friendly interface for smooth navigation.
- No hidden fees or surprise charges.,24/7 customer support availability.
- Flexible repayment options offered.
Cons
- High interest rates on short-term loans.
- Limited loan amounts available initially.
- Requires access to personal data.
- Not available in all regions.
- Strict eligibility criteria for users.
FAQs for Grant Cash Advance
What is Grant Cash Advance and how does it work?
Grant Cash Advance is a financial application designed to provide quick and easy cash advances for users in need of immediate funds. The app connects you with lenders, allowing you to apply for short-term loans directly from your mobile device. Once approved, funds are deposited into your account, usually within a few hours.
Is Grant Cash Advance safe to use?
Yes, Grant Cash Advance prioritizes user security by employing robust encryption protocols to protect your personal and financial information. The app partners with reputable lenders and follows industry standards to ensure that your data is handled with care. Always ensure your device is secure and up-to-date to maintain safety.
Are there any fees associated with using Grant Cash Advance?
While the app itself is free to download, fees may be associated with the cash advances offered. These fees can vary based on the lender, loan amount, and repayment terms. It’s important to review the terms and conditions for each advance to understand all costs before proceeding.
What are the eligibility requirements for applying through Grant Cash Advance?
To apply for a cash advance, you typically need to be at least 18 years old, have a valid bank account, and provide proof of a steady income. Specific requirements may vary by lender, so it’s important to check the criteria within the app to ensure you meet all necessary conditions.
How does repayment work for loans taken through Grant Cash Advance?
Repayment terms depend on the agreement with the lender. Generally, repayments are automatically deducted from your bank account on the due date. Users are encouraged to thoroughly review the repayment schedule, interest rates, and any potential late fees to avoid unexpected charges. Always ensure sufficient funds are available for repayments.

Grant Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@grantcash.com, visit https://grantcash.com, or review their https://documents.oasiscredit.com/privacy-policy.










